Oct 21, 2026
Cityscape 2026 Riyadh runs from 16 to 19 November at the Riyadh Exhibition & Convention Center (Malham), bringing developers, investors, banks and real estate decision-makers together for four days of project launches and deal-making.
The 2025 edition alone announced real estate deals worth SAR 237 billion in four days. That is why Cityscape is no longer only for developers: individual buyers and small investors now attend to see opening prices and payment plans before they reach the open market.
This guide covers what visitors look for most: the Cityscape 2026 date and venue, the exhibitor list, projects and offers, tickets and registration, how to get there, and how to prepare.
Cityscape 2026 Riyadh is the 2026 edition of Cityscape Global, which its organisers describe as the world's most attended real estate exhibition. It is organised by Tahaluf in partnership with the Real Estate General Authority (REGA), and this year's slogan is "The Capital of Real Estate".
The show in numbers:
It arrives months after Saudi Arabia's non-Saudi property ownership law took effect on 22 January 2026, which widened interest from abroad.
The Cityscape 2026 date is Monday 16 to Thursday 19 November 2026. Doors open to visitors from 12:00 pm to 10:00 pm every day.
The venue is the Riyadh Exhibition & Convention Center (Malham) in north Riyadh, about 30 km from King Khalid International Airport according to the organisers. Visitors often call it "Cityscape Malham".
The official exhibitor list is published on the Cityscape Global website and updates until the show opens. Confirmed so far:
Do not rely on the list alone: new launches may be announced during the show, so follow the show's and developers' channels across the four days.
The official ticket page describes mortgage solutions, ownership options and payment plans offered directly by developers and banks. In practice, Cityscape projects and offers come in three forms:
At the 2025 opening, Minister Majed Al-Hogail said real estate loans to individuals and companies reached about SAR 961 billion by Q2 2025 and citizen home ownership passed 65% at end-2024.
A show offer is not always the cheapest price in the market. Ask before you book:
Cityscape Riyadh 2026 offers three ticket categories: General, Business, and VIP. Each pass provides different benefits to suit visitors' needs, from exploring the exhibition to enjoying exclusive networking opportunities and premium hospitality services.
The General Pass is available free for a limited time, reduced from SAR 100. The offer ends on 15 November 2026. Benefits include:
The Business Pass costs SAR 2,438, including 15% VAT, reduced from SAR 3,000. It includes all General Pass benefits, plus:
The VIP Pass costs SAR 9,377, including 15% VAT, reduced from SAR 11,253. It offers a premium event experience with exclusive benefits, including:
The right ticket depends on your goals and budget. The General Pass is ideal for visitors exploring real estate opportunities, while the Business Pass suits professionals seeking networking opportunities and business services. The VIP Pass is designed for visitors who prefer exclusive access and premium hospitality.
Note: Ticket prices, promotional offers, and availability may change. Check the official Cityscape Riyadh 2026 ticketing page before registering.
To register: open the official ticket page or register by WhatsApp, choose a pass, enter your details exactly as on your ID (the pass is linked to your badge), pay by credit card if the pass is paid, then wait for the confirmation and badge emails. Each participant gets one pass only, fees are non-refundable and non-transferable, and accommodation and meals are not included.
The 2025 edition announced SAR 237 billion in deals over four days, including SAR 161.2 billion in the first two days. It also reported a 166,000 m² site (double 2023), 42 countries represented including 15 new ones, USD 6.1 trillion of real estate and infrastructure assets under management, 350+ investment meetings and 164,000+ attendees from 120+ countries.
Mada Properties is a professional real estate broker, not a developer, so we show you options as they stand in the whole market, not as a single developer presents them. Around a show, when offers and quick bookings pile up, a neutral broker compares launches with similar projects outside the show, checks the project's legal status and stays with you to closing. Contact us to compare what you see at the show with what is available today.
Cityscape 2026 Riyadh is the biggest chance this year to see the Saudi property market in one place: what will be launched, at what price and on what payment plan. It rewards visitors who arrive with a plan. Set your goal and budget before 16 November, register early, ask for every offer in writing and compare before you book.
Stay informed with expert-written articles and the latest trends in the real estate market.
August 27, 2026
Mortgage lending in Saudi Arabia operates inside a defined regulatory framework set by the Saudi Central Bank (SAMA), with each lender layering its own credit policy on top. The practical consequence is that eligibility, and the amount you can borrow, are not a verdict handed down at the branch. They are figures you can work out in advance.
That matters, because most property purchases in Riyadh today are financed over fifteen years or more, and the size of the financing available is what sets the range you can realistically shop in, not the other way round.
Real estate financing is an amount advanced by a bank or a finance company licensed by SAMA to buy a residential property, repaid in monthly instalments that typically run from fifteen to thirty years. The property is registered as security in the lender’s favour until the balance is settled in full.
One point of terminology worth clearing up early: in the Saudi market, "home loan," "mortgage" and "real estate financing" all describe the same thing. The meaningful difference is structural, most products offered in the Kingdom are built on Sharia-compliant contracts rather than interest-bearing lending, which is why you will see profit rates quoted rather than interest rates.
The contract structure varies between lenders. Three are common:
The difference between these is not just nomenclature. It affects when title passes to you, how early settlement is treated, and how insurance is handled. Ask which structure applies to your offer before you sign, not after.
Requirements are broadly consistent across lenders in the Kingdom; what varies are the thresholds:
Four of these decide the outcome more than the rest. They are worth taking in turn.
A complete, internally consistent file shortens the assessment and reduces the chance of rejection. Most lenders ask for:
Check that the details match across documents. A salary figure or employer name that reads differently on the salary certificate than on the bank statement is a routine cause of delay.
The Sakani programme, delivered with the Real Estate Development Fund (REDF), provides support to eligible Saudi nationals, including coverage of part of the profit margin up to a defined financing ceiling. General eligibility conditions:
The financing track adds further conditions: a minimum monthly income, a defined age band, the property being your first home, and an acceptable credit standing.
One point that is regularly missed: eligibility is determined through the Sakani platform, not by the bank. You can meet a lender’s commercial criteria and still fall outside the support criteria, or the reverse. Figures and ceilings are revised periodically, so use the official eligibility calculator rather than numbers quoted second-hand.
Financing is available to non-Saudis, on more conservative terms:
The wider ownership picture changed in 2026. Royal Decree M/14 took effect on 22 January 2026, consolidating non-Saudi property ownership under a single framework, and the Council of Ministers approved the executive regulations and the designated geographic zones in June 2026. Those zones include Riyadh. Because the rules are recent and documentation is still being published, confirm the current position before committing funds.
There is no single best lender, because the right one depends on your employment sector, where your salary is paid, and the type of property. The market offers three categories of provider:
Rather than looking for a ranking, compare offers on five points:
Because pricing and promotions shift, request written offers from more than one provider and compare them on the same day. That is the most reliable way to identify the best option for your particular position.
Most rejections come down to causes you can address before you apply:
A rejection is rarely final. Ask for the reason in writing — it tells you precisely what to fix before the next attempt.
Termination is governed by the terms of your contract and by SAMA regulation. Three situations account for most cases:
Termination is not the same as refinancing. Refinancing moves your existing facility to another provider on better terms while the obligation continues; termination ends the contractual relationship. Read the early settlement clause and its associated fees before you sign, and if you cannot reach a resolution with your lender, a complaint can be raised through SAMA’s official channels.
Mortgage requirements in Saudi Arabia are transparent and verifiable in advance, and the most common mistake is searching for a property before establishing borrowing capacity. The productive order is the reverse: calculate your debt burden ratio, review your SIMAH record, check your eligibility on Sakani, then search within the range that is actually open to you.
Once you're ready, speak with the Mada Properties team for expert guidance based on current market insights.
On a SAR 8,000 salary with no existing commitments, the maximum monthly instalment could reach roughly SAR 4,400 at a 55% debt burden ratio. The corresponding financing amount depends on the repayment term and profit rate offered, which is why the result differs between lenders.
Yes, on more conservative terms — a higher down payment and a repayment term tied to your iqama and employment contract. Sakani and REDF support is not available to non-citizens. Ownership itself now falls under Royal Decree M/14, in force since 22 January 2026, within designated zones that include Riyadh.
Indicative limits run between 55% and 65% of monthly income depending on borrower category and lender policy, and all existing commitments count towards it. Check SAMA’s responsible lending principles for the current position, as they are updated periodically.
SAMA raised the maximum loan-to-value ratio on a first home for Saudi citizens to 90%, putting the minimum down payment at 10%. It falls further on subsidised tracks for properties below a defined value ceiling.
Most products offered in the Kingdom are structured on Sharia-compliant contracts — commonly Murabaha or Ijara Muntahia Bittamleek — rather than interest-bearing lending, which is why lenders quote a profit rate rather than an interest rate.
August 27, 2026
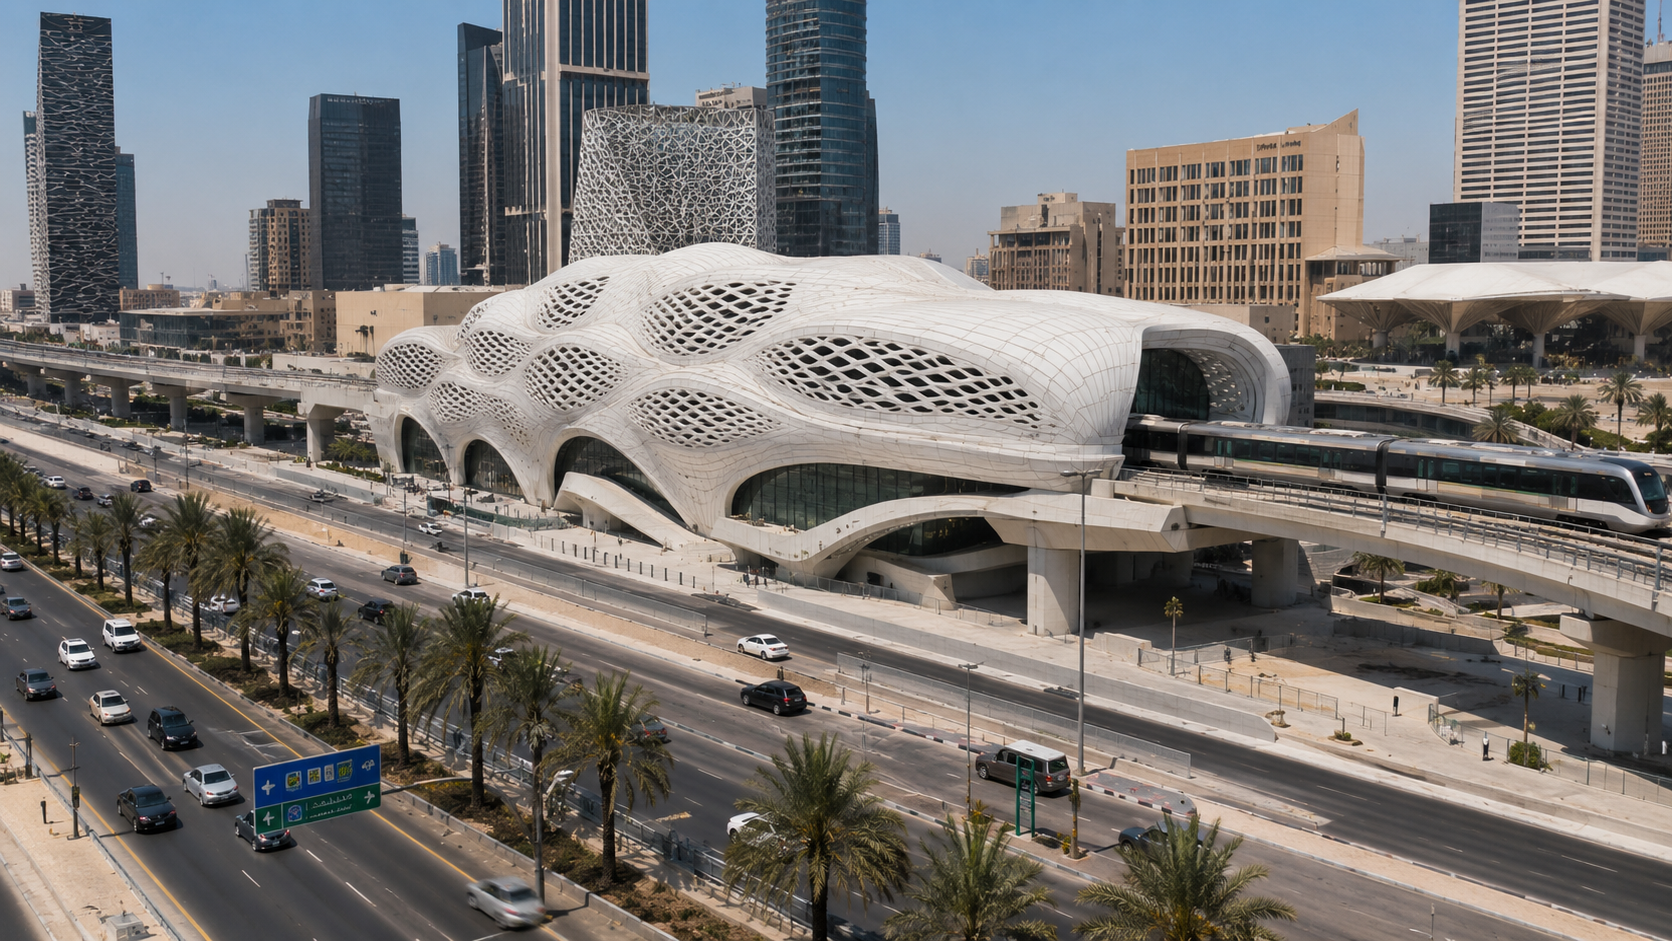
Riyadh Metro has changed how the capital’s property market is priced. Distance to the nearest station now sits alongside district and unit size in what buyers weigh, and the effect is already measurable: within a single district, homes near stations have grown in value at a different rate from those on its outer edges.
The station itself does not create value. Three mechanisms do.
A King Saud University study of the KAFD station recorded a 15 to 30 percent rise in vertical residential density, alongside a shift toward mixed-use.
Knight Frank’s 2025 analysis identified what it called a metro premium, comparing price growth near stations with growth in the same district’s outer areas.

Source: Knight Frank, 2025 (Q2 2023 – Q2 2025).
The same research estimates that 1.5 million of Riyadh’s 8.3 million residents live within a 15-minute walk of a station. King Saud University puts the uplift at 10 to 25 percent in market and rental value within 400 to 800 metres. The pattern is consistent: the gap widens in districts that were poorly connected before the metro, and narrows in established ones.
Dubai is the closest comparable market. Its metro has run since 2009, and its transaction data has been studied academically. The findings are less uniform than the headlines suggest.
JLL puts the walking-distance premium at between 5 and more than 25 percent, with high-density communities gaining far more than villa communities. The lesson for Riyadh: proximity pays, but sitting on top of a station does not.
CBRE recorded a premium of around 20 percent on homes near Elizabeth Line stations — and it materialised after the project was approved, well before services began in 2022. Over a longer window, prices near stations rose 80 percent between 2008 and 2023 against 74 percent in the surrounding areas: a net premium of six percentage points.
The takeaway is about timing. Most of the gain lands between announcement and opening, not after. That puts announced Riyadh Metro extensions, including the Red Line expansion toward Diriyah, in the window investors are watching now.
The districts that gain the most share three traits: density with room to grow, proximity to employment hubs, and weak connectivity before the metro.
Low-density villa communities gain less, since residents there still commute by car. Sitting on a metro line is not enough on its own — what matters is genuine walking distance to a station.
Evidence from comparable markets points one way: the metro effect is stronger on commercial property. Stations generate concentrated daily footfall, which serves retail and offices far more directly than a residential unit. That shows up in three places.
Residential remains less volatile and easier to exit. There, the metro effect shows as faster letting and firmer rents rather than a sharp price jump.
Expo 2030 will run on a six-million-square-metre site north of the capital, next to King Salman International Airport, with more than 40 million visits expected. Expo 2030 Riyadh Company estimates a GDP contribution of around SAR 241 billion during construction and roughly 171,000 direct and indirect jobs.
Both forces push the same way. Metro access determines how easily a district is reached; Expo determines how many people need to reach it. North Riyadh corridors close to both carry the strongest case. The usual caution applies to any event-led cycle: judge an asset on net yield and clear title, not projected price.
Riyadh continues to grow on the back of Vision 2030 and Expo 2030, and demand has followed into districts served by the network. Currently available through Mada Properties:
The Riyadh Metro effect on property values is real, but selective. It widens in mid-priced districts, narrows in established ones, and favours commercial over residential. Most of the growth arrives before a line opens, which makes timing the decisive variable.
Speak to the Mada Properties team for a recommendation built on market data rather than assumptions.
August 27, 2026
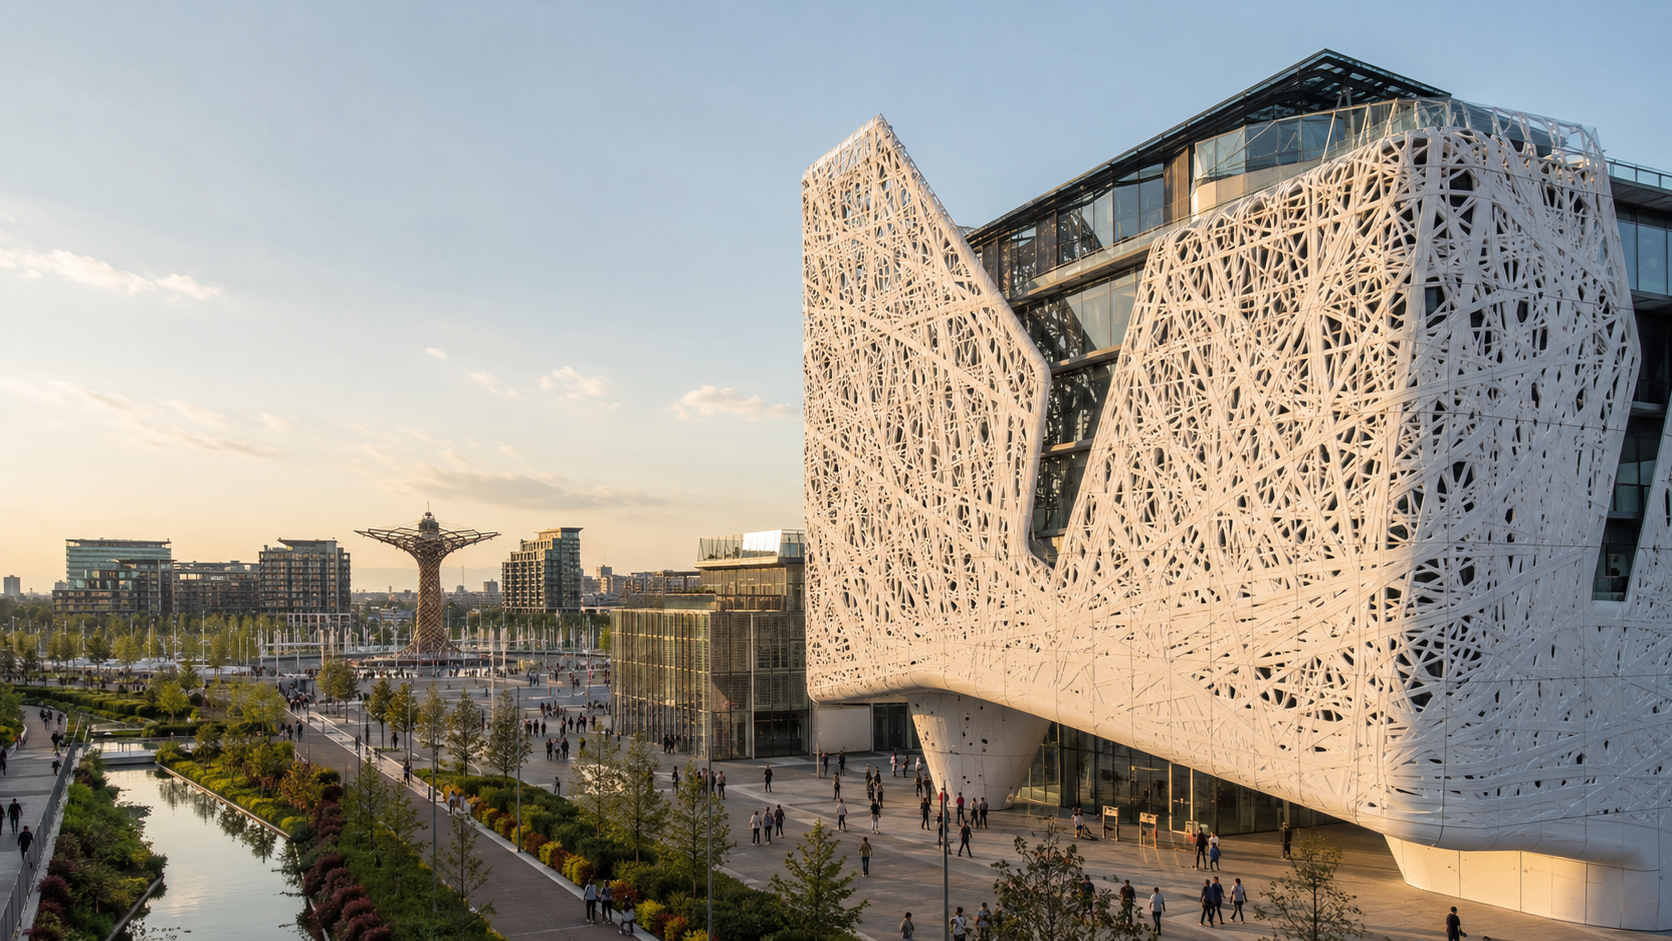
Milan hosted Expo 2015 for just six months. A decade later, the effect is still visible in its property prices and transaction volumes. For anyone watching Riyadh prepare for Expo 2030, that makes Milan worth a closer look.
Here is what happened in the Milan market before and after the event, and what Saudi investors can take from it.
Milan entered its hosting period still recovering from the 2008 crisis, with home prices around 30% below pre-crisis levels. Momentum built as the event approached: residential sales rose roughly 6.8%, and the city climbed from 24th to 12th in PwC's European city attractiveness ranking.
The fairground, northwest of the city in the Rho-Pero area, later became the Milan Innovation District, home to a hospital, research centres, a university campus and housing. Neighbouring areas felt it directly: in Cascina Merlata, beside the site, the average price per square metre rose from EUR 2,776 to EUR 3,993, up 44%, with transactions up 78%.
Activity moved before prices did. Between 2015 and 2021, residential transactions rose 48.2%, retail sales 60.5%, and offices jumped 179.7%. Rents in the city centre climbed around 40%. Prices rose 30% to 40% overall from 2015, and by 2022 sales volumes were double their pre-Expo level, with selling times halved.
Riyadh will host Expo 2030 in the north of the city, where the supporting infrastructure is already under construction. The early-entry window here is shorter than Milan's was.
A global event does not lift a market evenly. It lifts the locations the new infrastructure actually serves, which is where a professional broker earns their place.
At Mada Properties we track where value is forming and recommend accordingly. Let's talk about north Riyadh.